
 816-400-4477
Navigating the complexities of healthcare coverage can be daunting. Here's exactly how Medicare and Medicaid differ, who qualifies for each, and how dual eligibility actually works when both apply to you.
The short version
Medicare is federal health insurance primarily for people 65 and older, funded the same way nationwide. Medicaid is a joint federal-state program for people with limited income and resources, with eligibility and benefits that vary significantly by state. When someone qualifies for both, they're called "dual eligible," and Medicare typically pays first, with Medicaid covering some remaining costs. How much Medicaid actually helps depends heavily on which specific Medicaid eligibility level, or Medicare Savings Program, an individual qualifies for.
Sources: CMS Medicare and Medicaid program guidance; 2026 HHS Federal Poverty Guidelines.
What does it mean to be dual eligible for Medicare and Medicaid?
When an individual qualifies for both Medicare and Medicaid, they're referred to as being "dual eligible." In these instances, Medicare serves as the primary payer for medical services. Medicaid may then cover some portions of the expenses not covered by Medicare.
What is a Dual Special Needs Plan?
A Dual Special Needs Plan (D-SNP) is a specialized type of health insurance plan for individuals who qualify for both Medicare and Medicaid. These plans coordinate with both programs.
What's the difference between Medicare and Medicaid?
Medicare and Medicaid are two significant programs in the U.S. healthcare system, each addressing different healthcare needs and populations. They have distinct structures, funding mechanisms, and eligibility criteria.
What is Medicare?
Medicare is a federal program offering health insurance primarily to individuals aged 65 or older, as well as younger people with certain disabilities and diseases.
Medicare has four parts:
- Part A: covers hospital stays, skilled nursing facility care, hospice care, and some home health care.
- Part B: covers specific doctors' services, outpatient care, medical supplies, and preventive services.
- Part C: also known as Medicare Advantage Plans, are health insurance options offered by private companies approved by Medicare. Beneficiaries should scrutinize the plan details carefully before enrolling to ensure it meets their specific needs. It may be helpful to speak with a licensed insurance sales agent for a free plan comparison with no obligation to enroll.
- Part D: also known as Prescription Drug Plans.
How do you qualify for Medicare?
Medicare eligibility primarily targets individuals aged 65 or older, younger people with specific disabilities, and people with End-Stage Renal Disease (permanent kidney failure requiring dialysis or a transplant).
What is Medicaid?
On the other hand, Medicaid is a joint federal and state program designed to help individuals with limited income and resources cover medical costs. Although there are federal guidelines, each state establishes its own eligibility standards, determines the scope and duration of services, sets the payment rate for services, and administers its Medicaid program.
How do you qualify for Medicaid?
Medicaid eligibility involves meeting specific income and asset tests and can vary greatly from state to state. Certain groups automatically qualify for Medicaid, including low-income families, qualified pregnant women and children, and individuals receiving Supplemental Security Income (SSI). Some states have expanded their Medicaid programs to cover all adults below a certain income level.
State-specific factors affecting Medicaid eligibility may include family size, age, pregnancy status, and disability status, among others. For example, some states may cover adults up to a certain income level, pregnant women up to a higher income level, and children up to an even higher level. The eligibility rules can be complex, and specifics vary widely among states. Visit your state's Medicaid website or office to find out.
How to apply for Medicare and Medicaid
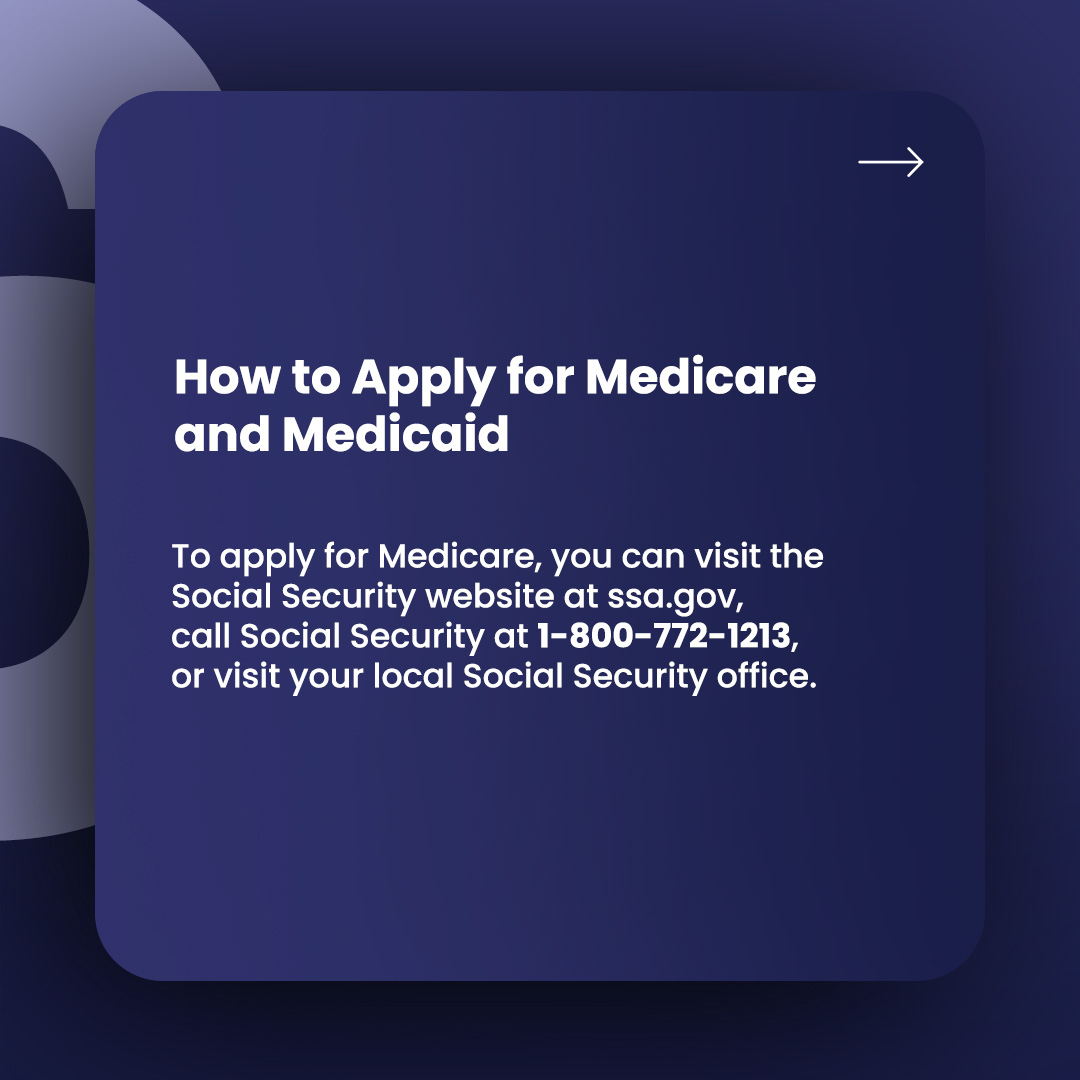
To apply for Medicare, you can visit the Social Security website at ssa.gov, call Social Security at 1-800-772-1213, or visit your local Social Security office.
To apply for Medicaid, you can visit the HealthCare.gov website, call the Marketplace Call Center at 1-800-318-2596, or contact your state Medicaid program directly.
Medicaid eligibility levels and dual eligibility
Medicaid eligibility levels refer to the income thresholds set by each state within federal guidelines that determine who is eligible for Medicaid benefits. These levels are often expressed as a percentage of the Federal Poverty Level (FPL), a measure of income issued annually by the Department of Health and Human Services.
As per the Affordable Care Act, all states were required to cover children up to at least 133% of the FPL, but most states have chosen to cover children at even higher income levels. For adults, the eligibility levels can vary significantly from state to state. For 2026, the FPL for a single individual is $15,960 annually.
To find the specific eligibility levels in your state, you can visit your state's Medicaid website or use resources like the Kaiser Family Foundation (KFF), which publishes state-by-state Medicaid eligibility levels for various groups.
Firstly, it's important to note that Medicare typically acts as the primary payer, which means it pays first for healthcare services. Medicaid then provides additional assistance, acting as a secondary payer. For dual eligibles, Medicaid can assist with Medicare. The extent of this assistance can depend on the Medicaid eligibility level of the individual. For instance, some dual eligibles may qualify for full Medicaid benefits, while others may only qualify for help with certain Medicare costs.
One example is the Qualified Medicare Beneficiary (QMB) Program. This program is for people with income at or below 100% of the Federal Poverty Level. Individuals in the QMB program get assistance from Medicaid to pay their Medicare expenses.
| QMB level | What it covers |
|---|---|
| QMB Only | Assistance with Medicare costs, without additional Medicaid benefits |
| QMB Plus (QMB+) | Assistance with Medicare costs, plus full Medicaid coverage |
There are also other Medicare Savings Programs (MSPs) for individuals with higher income levels, such as the Specified Low-Income Medicare Beneficiary (SLMB) Program and the Qualifying Individual (QI) Program.
Specified Low-Income Medicare Beneficiary (SLMB) Program
The SLMB program is for those who have income that's slightly higher than the QMB limits. To qualify for the SLMB program, your income must be between 100% and 120% of the Federal Poverty Level (FPL). The asset limit for the SLMB program is $9,950 for an individual and $14,910 for a couple in 2026.
Qualifying Individual (QI) Program
The QI program is for those with incomes higher than the SLMB limits. To qualify for the QI program, your income must be between 120% and 135% of the FPL. The asset limit for the QI program is the same as that of the SLMB program. It's important to note that you must apply every year for QI benefits, and these benefits are granted on a first-come, first-served basis.
These programs help lower-income individuals afford the often high costs associated with Medicare. Each state may have slightly different income and asset limits, so it's important to check with your state's Medicaid office to see if you qualify. In summary, Medicaid eligibility levels can impact how much Medicaid pays when coordinating with Medicare by determining the extent of assistance with Medicare costs.
It's worth remembering that none of these Medicare Savings Program distinctions matter unless you actually apply through your state's Medicaid office — eligibility isn't automatic just because your income happens to fall within a given range.
Medicaid redetermination and its impact on Medicare/Medicaid dual eligibility
Medicaid redetermination is a process that occurs typically every year to verify that individuals still meet the eligibility requirements for Medicaid. This process can have significant implications for those who are dually eligible for both Medicare and Medicaid.
If a dual-eligible individual is affected by the Medicaid redetermination process and loses their Medicaid eligibility, they could potentially lose access to Dual Eligible Special Needs Plans (D-SNPs) with Medicare. It's important to understand these potential changes and prepare accordingly.
If you have questions or concerns about your eligibility or coverage, it may be helpful to consult with a healthcare professional, social worker, licensed insurance sales agent, or legal advisor who specializes in these areas.
Working with a licensed health insurance sales agent can be a great way to navigate the complex coverage options available. They can also explain the differences between plans and help you figure out which plan fits your needs and budget. Ultimately, a licensed insurance sales agent can help you make an informed decision about the coverage that suits your needs.
A quick checklist for understanding dual eligibility
- Confirm whether you qualify for Medicare based on age, disability, or End-Stage Renal Disease, separately from any Medicaid eligibility.
- Check your specific state's Medicaid income and asset limits, since these vary significantly and your own state's rules are what actually apply to you.
- If your income is above full Medicaid limits but still low, ask about QMB, SLMB, and QI specifically, rather than assuming you don't qualify for any help.
- Understand which program is your primary payer and which is secondary, so you know what order your bills are actually processed in.
- Stay on top of your state's Medicaid redetermination schedule, since losing Medicaid eligibility can also affect a D-SNP plan tied to it.
For the authoritative federal sources on these programs, Medicare.gov confirms current eligibility and Medicare Savings Program rules directly, and Medicaid.gov maintains official eligibility information and state-by-state resources.
Frequently asked questions about Medicare vs. Medicaid
Have a question that isn't answered below? Our full health insurance FAQ page covers more, and our blog has deeper guides on Medicare topics.
What is the main difference between Medicare and Medicaid?
Can you have both Medicare and Medicaid at the same time?
What is the Qualified Medicare Beneficiary (QMB) Program?
What's the difference between SLMB and QI?
What happens to my coverage during Medicaid redetermination?
Does it cost more to work with a broker to understand dual eligibility?
Not sure how Medicare and Medicaid might work together for you? Let's find out together. At no cost.
A licensed Apollo Medicare advisor can walk through your specific eligibility for Medicare, Medicaid, and Medicare Savings Programs, and explain exactly how they'd coordinate for your situation.
Explore Medicare Advantage, Medicare Supplement plans, or learn more about our licensed advisors.
Disclaimer: This guide is general educational information about Medicare and Medicaid and is not insurance, tax, or legal advice. Eligibility rules, income limits, and benefits vary significantly by state and change over time. Verify current details with Medicare.gov, Medicaid.gov, your state's Medicaid office, or a licensed Apollo Health Insurance agent before making a coverage decision. Apollo Health Insurance is a licensed insurance brokerage; we are not affiliated with the federal government or any state agency.

I am a professional content writer specializing in the health insurance field. My work primarily focuses on simplifying the complexities of healthcare coverage, aiming to provide clarity and insight into an often confusing subject. Empowering people to make informed decisions about their well-being is my passion. At Apollo Health Insurance, we share that commitment. Apollo Health Insurance stands at the forefront of securing the best healthcare coverage for individuals, ensuring affordability without compromising on quality.
0 Comments