
 816-400-4477
Understanding Special Enrollment Periods is crucial for effective healthcare management. SEPs let you make changes to your coverage outside the regular enrollment window — here's exactly what qualifies, and how long you have to act.
The short version
A Special Enrollment Period is a window outside the annual Open Enrollment Period during which you can enroll in or change health coverage, triggered by a qualifying life event like marriage, having a baby, losing other coverage, or moving. For ACA Marketplace plans, most SEPs last 60 days from the qualifying event. Medicare has its own, separate SEP system with different rules and timeframes, including a distinct FEMA disaster SEP that runs a full four months rather than 60 days. Knowing which system applies to you, and having the right documentation ready, is what actually determines whether you can act in time.
Sources: HealthCare.gov qualifying life event rules; CMS Medicare FEMA disaster Special Enrollment Period guidance.
SEPs for qualifying life events
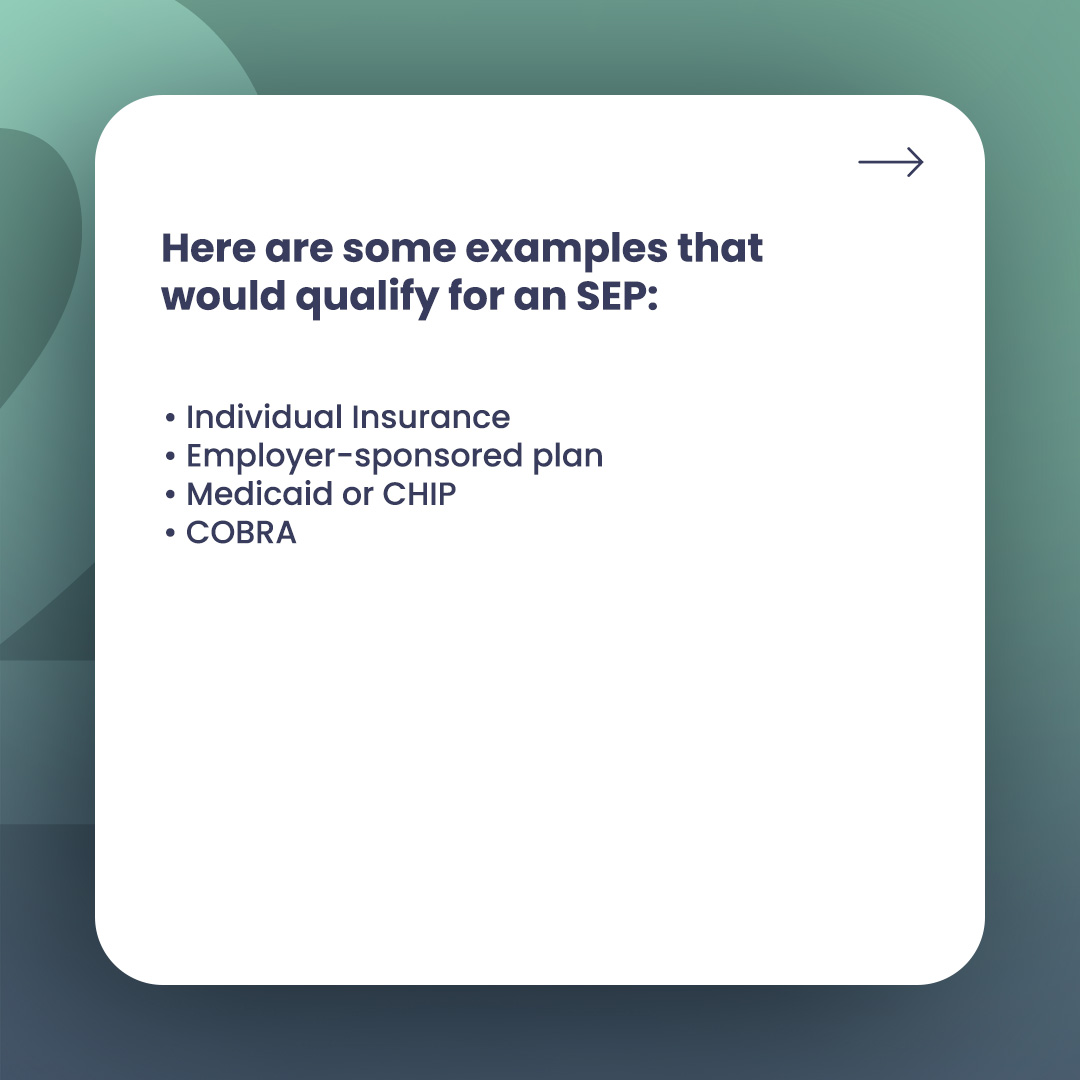
There are several SEPs that are important to be aware of to ensure effective personal healthcare management. Health Insurance Marketplace SEPs are triggered by certain life events or situations, known as qualifying life events. Qualifying life events that trigger eligibility for a Health Insurance Marketplace SEP include:
- Losing health coverage: the Health Insurance Marketplace recognizes various scenarios under which loss of qualifying health coverage can trigger an SEP. It's important to note that losing coverage that doesn't qualify as minimum essential coverage does not entitle you to an SEP. Also, voluntarily ending coverage, including not paying your premium, doesn't make you eligible for an SEP.
- Changes in household: these changes could include getting married, having a baby, adopting a child, or placing a child in foster care. A death in the family could also qualify you for an SEP.
- Changes in residence: moving to a new home in a new ZIP code or county, moving to the U.S. from a foreign country or a U.S. territory, or moving to or from a shelter or transitional housing may trigger an SEP.
- Changes in income: a significant change in your income can affect your health insurance coverage. This could be due to a job loss, a substantial decrease or increase in your salary, or a change in your household size, which alters your household income. Any of these changes could impact your eligibility for premium tax credits or cost-sharing reductions, triggering an SEP. To prove this significant life event, you'd need to provide documents like recent pay stubs reflecting your income change, a letter from your employer confirming the change in your employment status, or tax returns showing a change in income.
- Gaining membership in a federally recognized tribe or ANCSA Corporation shareholder status: this status comes with unique rights and benefits, including health coverage options. To confirm this life event, you'd need to provide an official letter or certificate from the tribe or corporation.
- Becoming a U.S. citizen: gaining U.S. citizenship changes your rights and options for health coverage. To prove this life event, you'd need to provide a certificate of naturalization or citizenship, or a U.S. passport.
- Leaving incarceration: if you've recently been released from a correctional facility, this qualifies you for an SEP, since it significantly affects your living situation and potential access to health care. You'd need to provide a release form, parole documentation, or a letter from the prison or jail.
- AmeriCorps members starting or ending their service: beginning or ending AmeriCorps service can significantly affect your income and access to health coverage. You'd need to provide a letter from AmeriCorps confirming the start or end date of your service.
What would qualify for an SEP?
Here are some examples that would qualify for an SEP:
- Individual insurance: if you're dropped from an individual health plan, not through your employer, during the year, either because the insurer stopped selling the plan or for other reasons, you qualify for an SEP.
- Employer-sponsored plan: you're eligible for an SEP if you lose health coverage through your job or the job of a family member, including when a job ends or you lose coverage due to a reduction in work hours.
- Medicaid or CHIP: one important point to note is that voluntary termination of Medicaid or CHIP, or losing Medicaid or CHIP coverage because you didn't pay premiums, does not qualify you for an SEP. Similarly, losing coverage because you chose not to renew it also does not qualify you for an SEP.
Losing Medicaid coverage can be a stressful event, but it's important to know that it can also open the door to new health insurance opportunities through the Health Insurance Marketplace. When you lose Medicaid eligibility, you may qualify for a Special Enrollment Period, a crucial time outside the yearly Open Enrollment Period when you can sign up for health insurance. The SEP triggered by losing Medicaid lasts for 60 days from the day your Medicaid coverage ends.
During this period, you can choose a new health plan from the Marketplace. This provides a safety net, ensuring that even if you lose Medicaid coverage, you won't be left uninsured. You'll have the chance to explore a variety of health plans and select one that fits your current healthcare needs and budget. To apply for an SEP, you'll need to provide documentation showing the end of your Medicaid coverage. Once your application is accepted, your new Marketplace coverage can start the first day of the month after you enroll in a plan.
- COBRA: if your COBRA continuation coverage expires, you're entitled to an SEP. However, voluntarily ending COBRA before it expires does not qualify you for an SEP.
- Coverage under a parent's plan: if you turn 26 and can no longer be on a parent's health insurance, you qualify for an SEP.
The FEMA disaster/emergency SEP: Marketplace vs. Medicare
The FEMA Special Enrollment Period is a period during which individuals affected by a disaster declared by the Federal Emergency Management Agency (FEMA) can enroll in, disenroll from, or switch their health insurance plans. It's important to understand that this isn't one single program; the ACA Marketplace and Medicare each run their own separate FEMA disaster SEP, with different timeframes.
| Program | SEP duration | Key eligibility detail |
|---|---|---|
| ACA Marketplace | 60 days | From the start of the FEMA-declared incident period |
| Medicare | 4 months | Must have had another valid Medicare election period the disaster prevented you from using |
For ACA Marketplace coverage, the FEMA SEP is designed to provide relief for people who were unable to complete enrollment due to the disaster, or who live in an area where a disaster has been officially declared. This version of the SEP typically lasts for 60 days from the start of the incident period.
For Medicare, the FEMA disaster SEP is a separate, distinct benefit with its own rules: it runs for a full four calendar months from the start of the declared incident period, specifically for beneficiaries who had another valid Medicare enrollment opportunity at the time of the disaster, such as the annual Medicare Advantage/Part D open enrollment window, but were unable to use it because of the emergency. This four-month Medicare-specific window is meaningfully longer than the Marketplace's 60-day version, so it's worth confirming which system actually applies to your specific coverage before assuming either timeframe.
The first step to qualifying for either FEMA SEP is to be in an area that FEMA has officially declared as an emergency or major disaster zone. This includes both individuals who currently reside in these areas, and also those who resided there at the start of the incident period. It's not just about your physical location, either: the SEP also extends to individuals who don't live in the affected areas but rely on help making healthcare decisions from friends or family members who do reside in those areas.
Remember, the exact requirements can vary based on the specific circumstances of the disaster and the rules of the health coverage program. It's important to check with the relevant authorities or organizations for the most accurate information. If you believe you qualify for a FEMA SEP but are having trouble with the application process, consider reaching out to a social worker or a licensed insurance sales agent.
A quick checklist for using an SEP
- Confirm which specific qualifying life event applies to your situation, and its exact timeframe, before assuming a generic "60 days" window applies everywhere.
- Gather the correct supporting documentation for your specific event before you apply, rather than discovering what's needed partway through.
- If you're affected by a FEMA-declared disaster, confirm whether you're applying through the ACA Marketplace (60 days) or Medicare (4 months), since the two systems run separately.
- Apply as early as possible within your window, since processing and plan start dates can take time even after a successful application.
- Talk to a licensed broker if you're unsure whether your specific situation qualifies, rather than assuming it doesn't and missing the window entirely.
For the authoritative federal sources on these rules, HealthCare.gov publishes the current list of qualifying life events and required documentation directly, and Medicare.gov confirms Medicare's own separate enrollment period rules.
Frequently asked questions about Special Enrollment Periods
Have a question that isn't answered below? Our full health insurance FAQ page covers more, and our blog has deeper guides on specific enrollment topics.
What is a Special Enrollment Period?
How long do I have to use a Special Enrollment Period?
Does losing Medicaid or CHIP always qualify me for an SEP?
Can a change in income trigger a Special Enrollment Period?
Are the ACA Marketplace and Medicare FEMA disaster SEPs the same program?
Does it cost more to use a broker to figure out if I qualify for an SEP?
Think you might qualify for a Special Enrollment Period? Let's find out together. At no cost.
An Apollo agent can confirm whether your specific situation qualifies for an SEP, help you gather the right documentation, and make sure you don't miss your enrollment window.
Explore ACA Marketplace plans, Medicare coverage, or learn more about our licensed advisors.
Disclaimer: This guide is general educational information about Special Enrollment Periods and is not insurance, tax, or legal advice. SEP rules, documentation requirements, and timeframes vary by program and change over time. Verify current details with HealthCare.gov, Medicare.gov, or a licensed Apollo Health Insurance agent before making a coverage decision. Apollo Health Insurance is a licensed insurance brokerage; we are not affiliated with the federal government or any state agency.

I am a professional content writer specializing in the health insurance field. My work primarily focuses on simplifying the complexities of healthcare coverage, aiming to provide clarity and insight into an often confusing subject. Empowering people to make informed decisions about their well-being is my passion. At Apollo Health Insurance, we share that commitment. Apollo Health Insurance stands at the forefront of securing the best healthcare coverage for individuals, ensuring affordability without compromising on quality.
0 Comments